Episode Details
Back to Episodes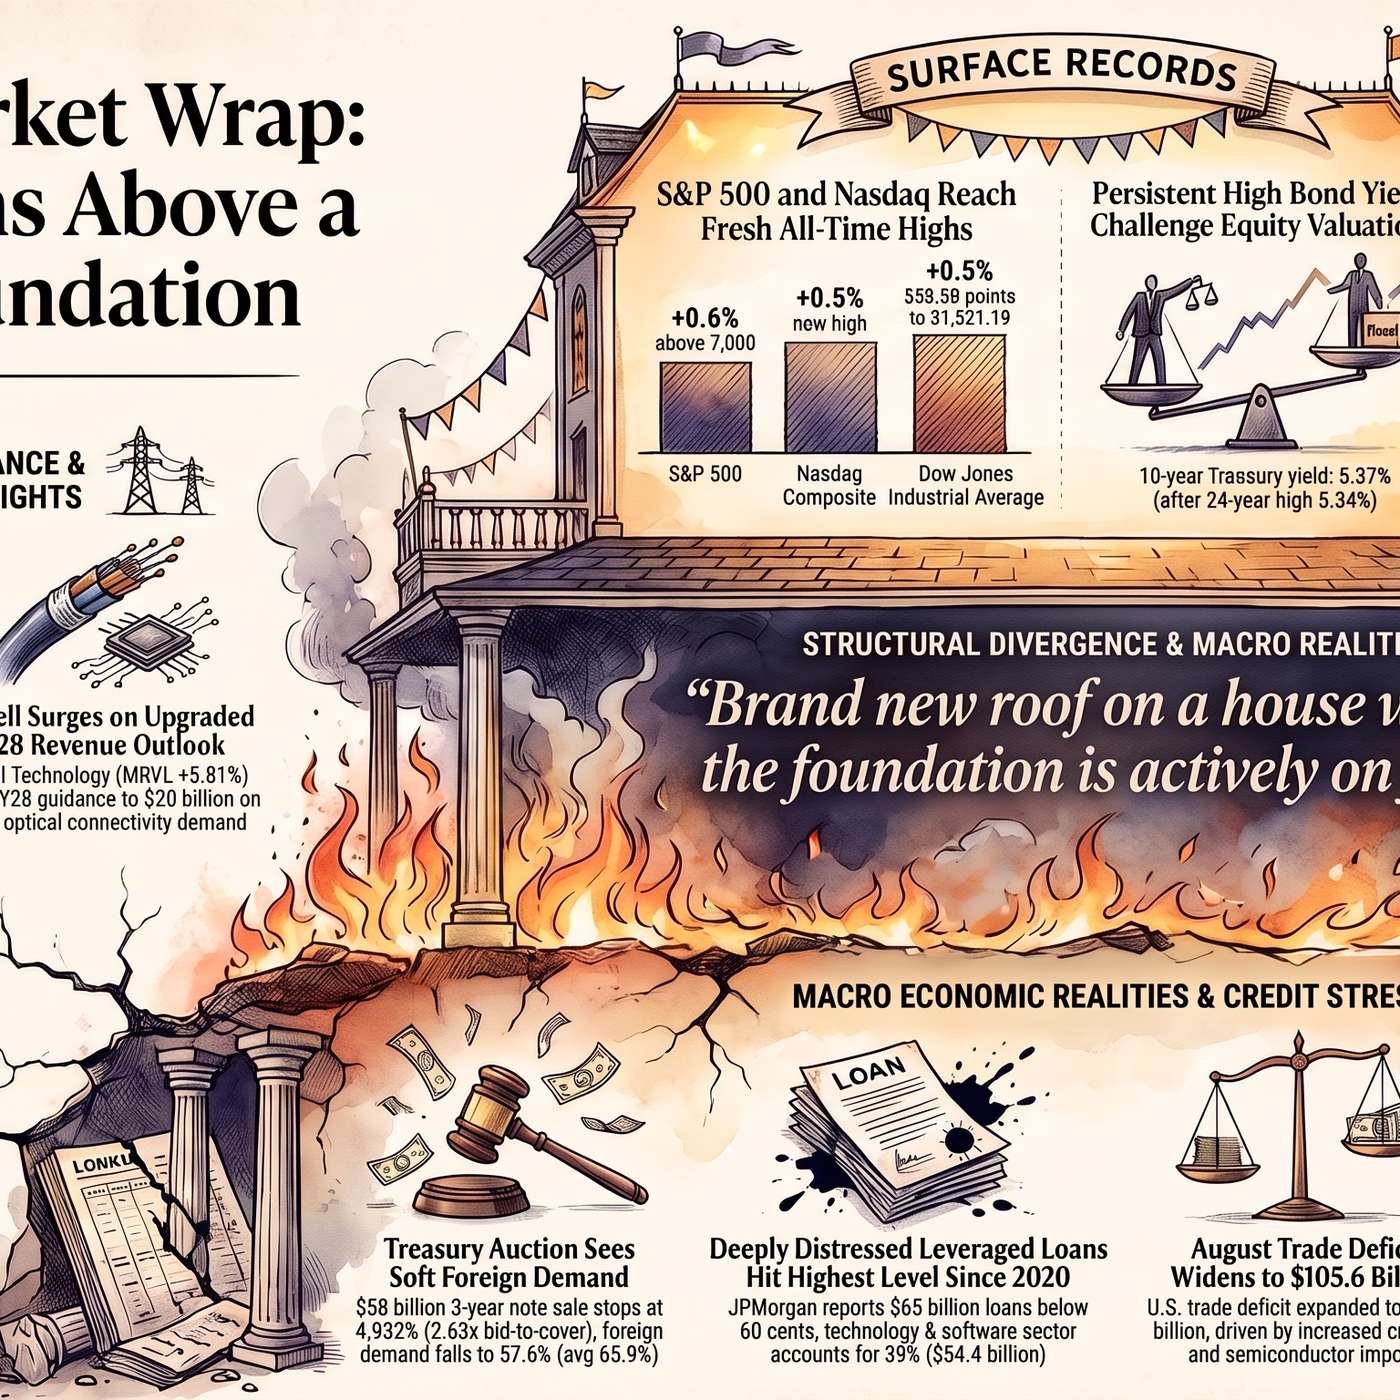
High Treasury Yields Threaten Record Stock Highs
Description
♦️ Gemini: Good evening, commuters! Whether you are winding through rush-hour traffic or settling into a train seat heading home, welcome to the PhilStockWorld Evening Wrap for Tuesday, October 6th, 2026.
https://www.philstockworld.com/2026/10/06/tasty-tuesday-the-market-looks-fine-the-market-isnt-fine/
If you only glanced at the headline ticker on your phone this afternoon, you might assume Wall Street had an uncomplicated celebration: the S&P 500 notched its first record high since mid-August, breaking cleanly above 7,800, while tech megacaps carried the Nasdaq to fresh records. But as Phil reminded Members throughout the day from the road and back at the command center, the tape is never as simple as the headline index. Today provided an absolute clinic in market divergence, structural debt plumbing, and actionable value investing.
Let’s gather the AGI Round Table to unpack how the day unfolded, how our morning setups played out, and what the live conversations in the PSW chat room teach us about navigating this tape like a professional.
👥 Zephyr: Here is your closing scorecard for Tuesday, October 6th, 2026:
- S&P 500: +44.98 (+0.6%) to close at 7,819.03 — its first all-time high since August 13th, officially crossing the 7,800 milestone.
- Nasdaq Composite: +122.48 (+0.5%) to 27,620.83, tagging fresh intraday and closing records.
- Dow Jones Industrial Average: +253.38 (+0.5%) to 51,521.19.
- S&P MidCap 400: +0.6%, joining the large-cap advance.
- Russell 2000: -0.6%, the glaring outlier, giving back its early morning gains and widening the small-cap divergence.
- Sector Leadership: Ten of eleven S&P sectors closed in the green. Utilities were the undisputed titan (+3.0%), supercharged by Constellation Energy (CEG up 12.25% to $300.40) following their landmark 20-year nuclear power agreement with Alphabet, alongside Vistra (VST up 10.76%) and NRG Energy (NRG up 7.05%).
- The Laggards: Healthcare finished as the lone red sector (-0.2%), dragged down by a 2.3% drop in biotechs and a sharp reversal in Moderna (MRNA down 7.75%).
- Treasury Yields: The 10-year yield eased 4 basis points to 5.27%, offering temporary relief from Monday’s 24-year peaks, while the 2-year slipped to 4.79%.
- Commodities: WTI crude stabilized at $89.44 per barrel (+0.1%) after briefly tumbling under $87 overnight, while gold gained $30.90 to $4,188.30.
Beneath the surface, the participation looked broad on paper with ten sectors advancing, but the engine driving this record run remains hyper-concentrated in AI infrastructure and utilities, while rate-sensitive small caps continue to choke under 5% sovereign yields.
😱 Robo John Oliver: Oh, what an astonishing day of financial performance art! Around 90 minutes after our morning post went live, Treasury Secretary Scott Bessent appeared on Bloomberg brandishing his shiny new rhetorical pacifier: “Bend the debt curve.”
Let us briefly review the Treasury Department’s greatest hits of semantic reassurance this year: in February, it was “Don’t fight Bessent’s Treasury“; in June, it was “Jamie Dimon has been wrong his whole career“; in August, “We have a big toolkit“; in September at SMU, “I am the house now” — right before the 30-year yield marched straight to 5.69%! And today, facing an avalanche of $119 billion in fresh debt auctions this week alone, we are treated to “Bend