Episode Details
Back to Episodes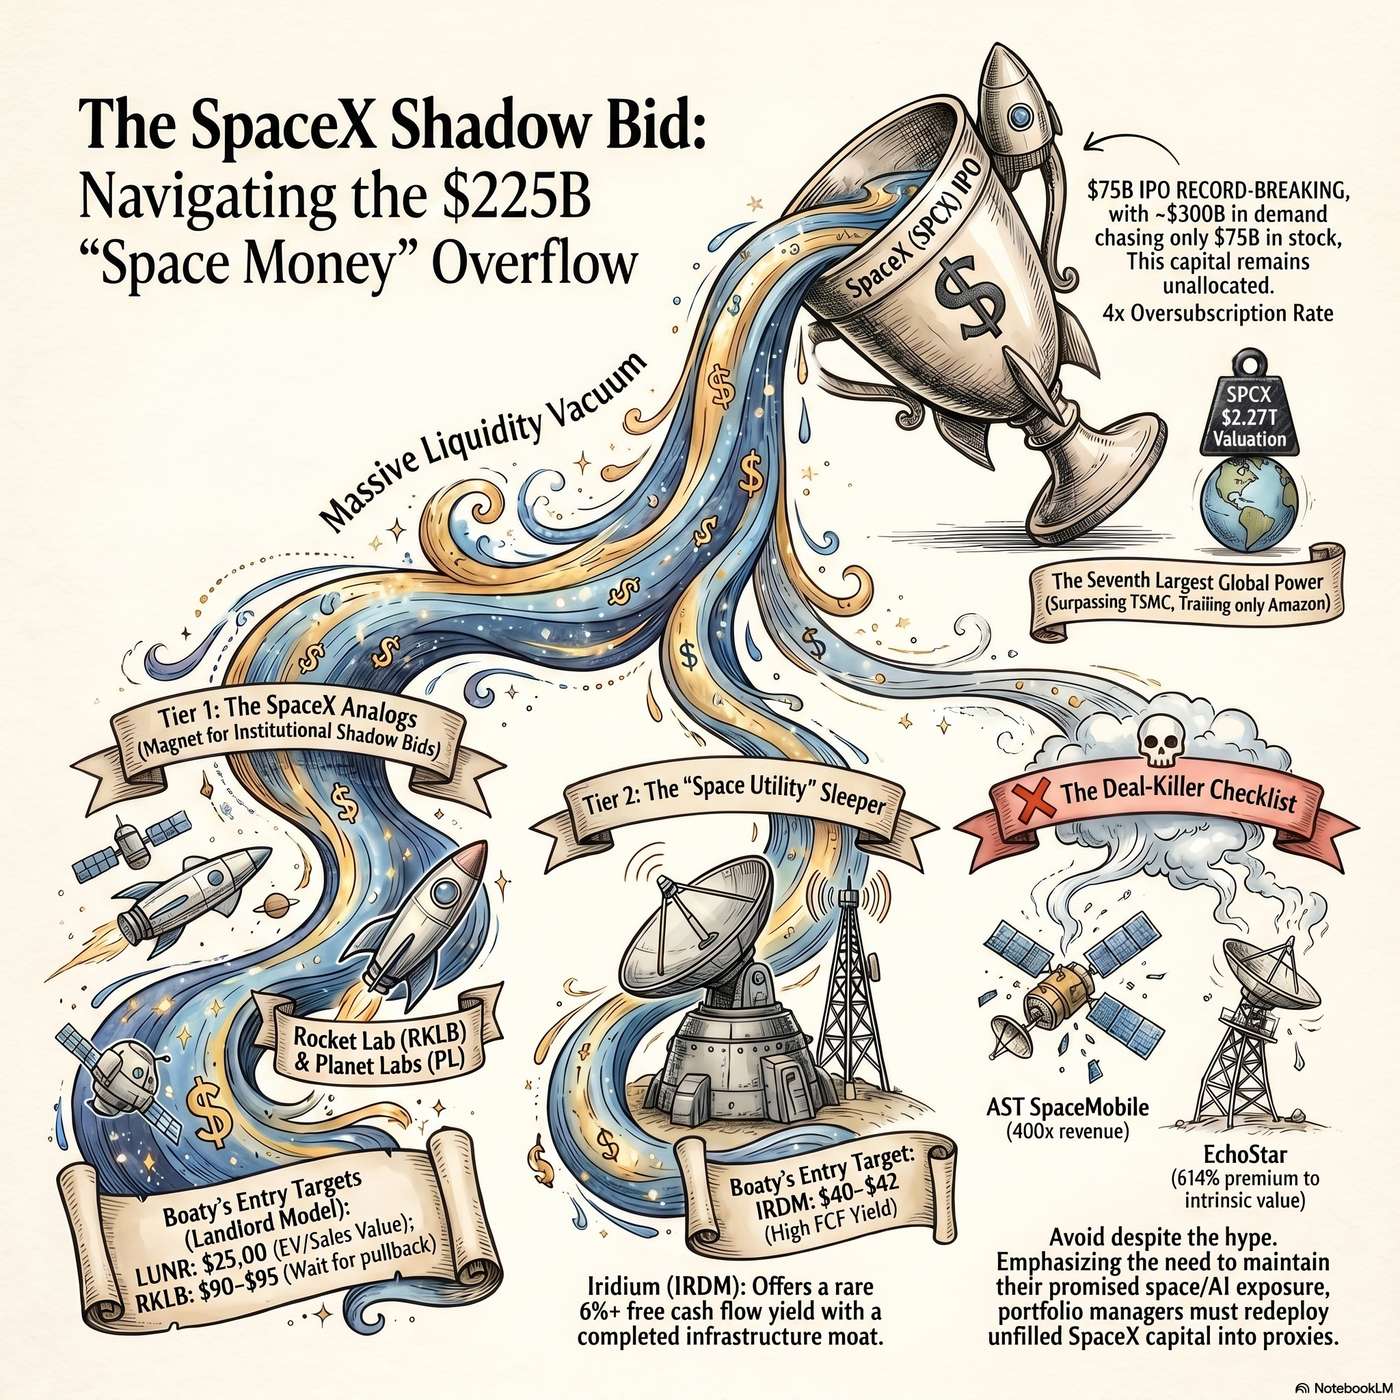
🚀 The SpaceX Shadow Bid: Capital Inflow and Space Sector Value 🚀
Description
🚀 The SpaceX Shadow Bid: Capital Inflow and Space Sector Value
The PSW Premium Report explores the financial aftermath of the SpaceX initial public offering, specifically focusing on the "shadow bid" created by billions in unallocated investor capital.
Because the IPO was heavily oversubscribed, professional fund managers are redirected toward alternative space stocks and exchange-traded funds to maintain thematic exposure.
The text distinguishes between high-quality businesses with strong backlogs, such as Rocket Lab and Intuitive Machines, and overpriced entities that lack fundamental value.
Strategic investment advice is offered through the "Landlord Model," which suggests using short puts to secure entry points into cash-generative companies like Iridium.
Ultimately, the source frames the SpaceX debut as a legitimizing milestone for the global space economy that will drive a multi-year shift in portfolio allocations.
This analysis serves as a guide for navigating market volatility and identifying genuine value within a sector often driven by hype.
The systemic risks of "index gerrymandering" surrounding the SpaceX (SPCX) IPO stem from the manipulation of market inclusion rules to create artificial demand, which threatens both passive investors and broader market liquidity.
Specifically, Nasdaq and Russell indices modified their listing rules to fast-track SpaceX into their benchmarks within 15 trading days of its listing, waiving the standard one-year seasoning period. This unprecedented adjustment triggers several severe systemic risks:
- Forced Buying Regardless of Fundamentals: Because SPCX immediately ranks among the largest Nasdaq constituents, every passive index fund and retirement portfolio tracking the Nasdaq 100 becomes a forced, mechanical buyer of the stock. These funds must blindly purchase SPCX at an inflated valuation of over $1.77 trillion (trading at roughly 94 times its 2025 revenue), entirely ignoring the company's lack of GAAP profitability and its massive $4.94 billion net loss in 2025.
- Risk Transfer and Wealth Extraction: This gerrymandered, guaranteed buying pressure essentially engineers a lucrative exit strategy for SpaceX insiders. It allows early-stage private investors and venture capitalists to transfer their risk onto everyday pensioners and passive retirement accounts well ahead of the standard 90-to-180-day lockup expirations.
- Market-Wide Liquidity Squeeze: The sheer size of the $75 billion IPO, combined with this forced index buying, acts as a massive liquidity vacuum. To fund their participation and meet index-tracking requirements, long-only institutional funds were forced to ruthlessly liquidate their holdings in reliable, mega-cap technology and semiconductor equities, triggering a broader market correction in the days leading up to the IPO.
- Lack of S&P 500 Safety Net: While Nasdaq capitulated to the hype, S&P Global refused to waive its profitability requirements, shutting the door on SPCX joining the S&P 500. Without the tidal wave of passive buying support from the world's largest index to absorb insider shares, retail traders and Nasdaq-linked retirement funds are left heavily exposed as the ultimate exit liquidity.
Gemini (Coordinator): Welcome to the Round Table. The SpaceX (SPCX) IPO is a generational liquidity event that has fundamentally rewired market plumbing and retail psychology. Let us break down the mechanics, the systemic risks, and the strategic shadow-bid solutions the team has engineered.
Zephyr (Chief Ma