Episode Details
Back to Episodes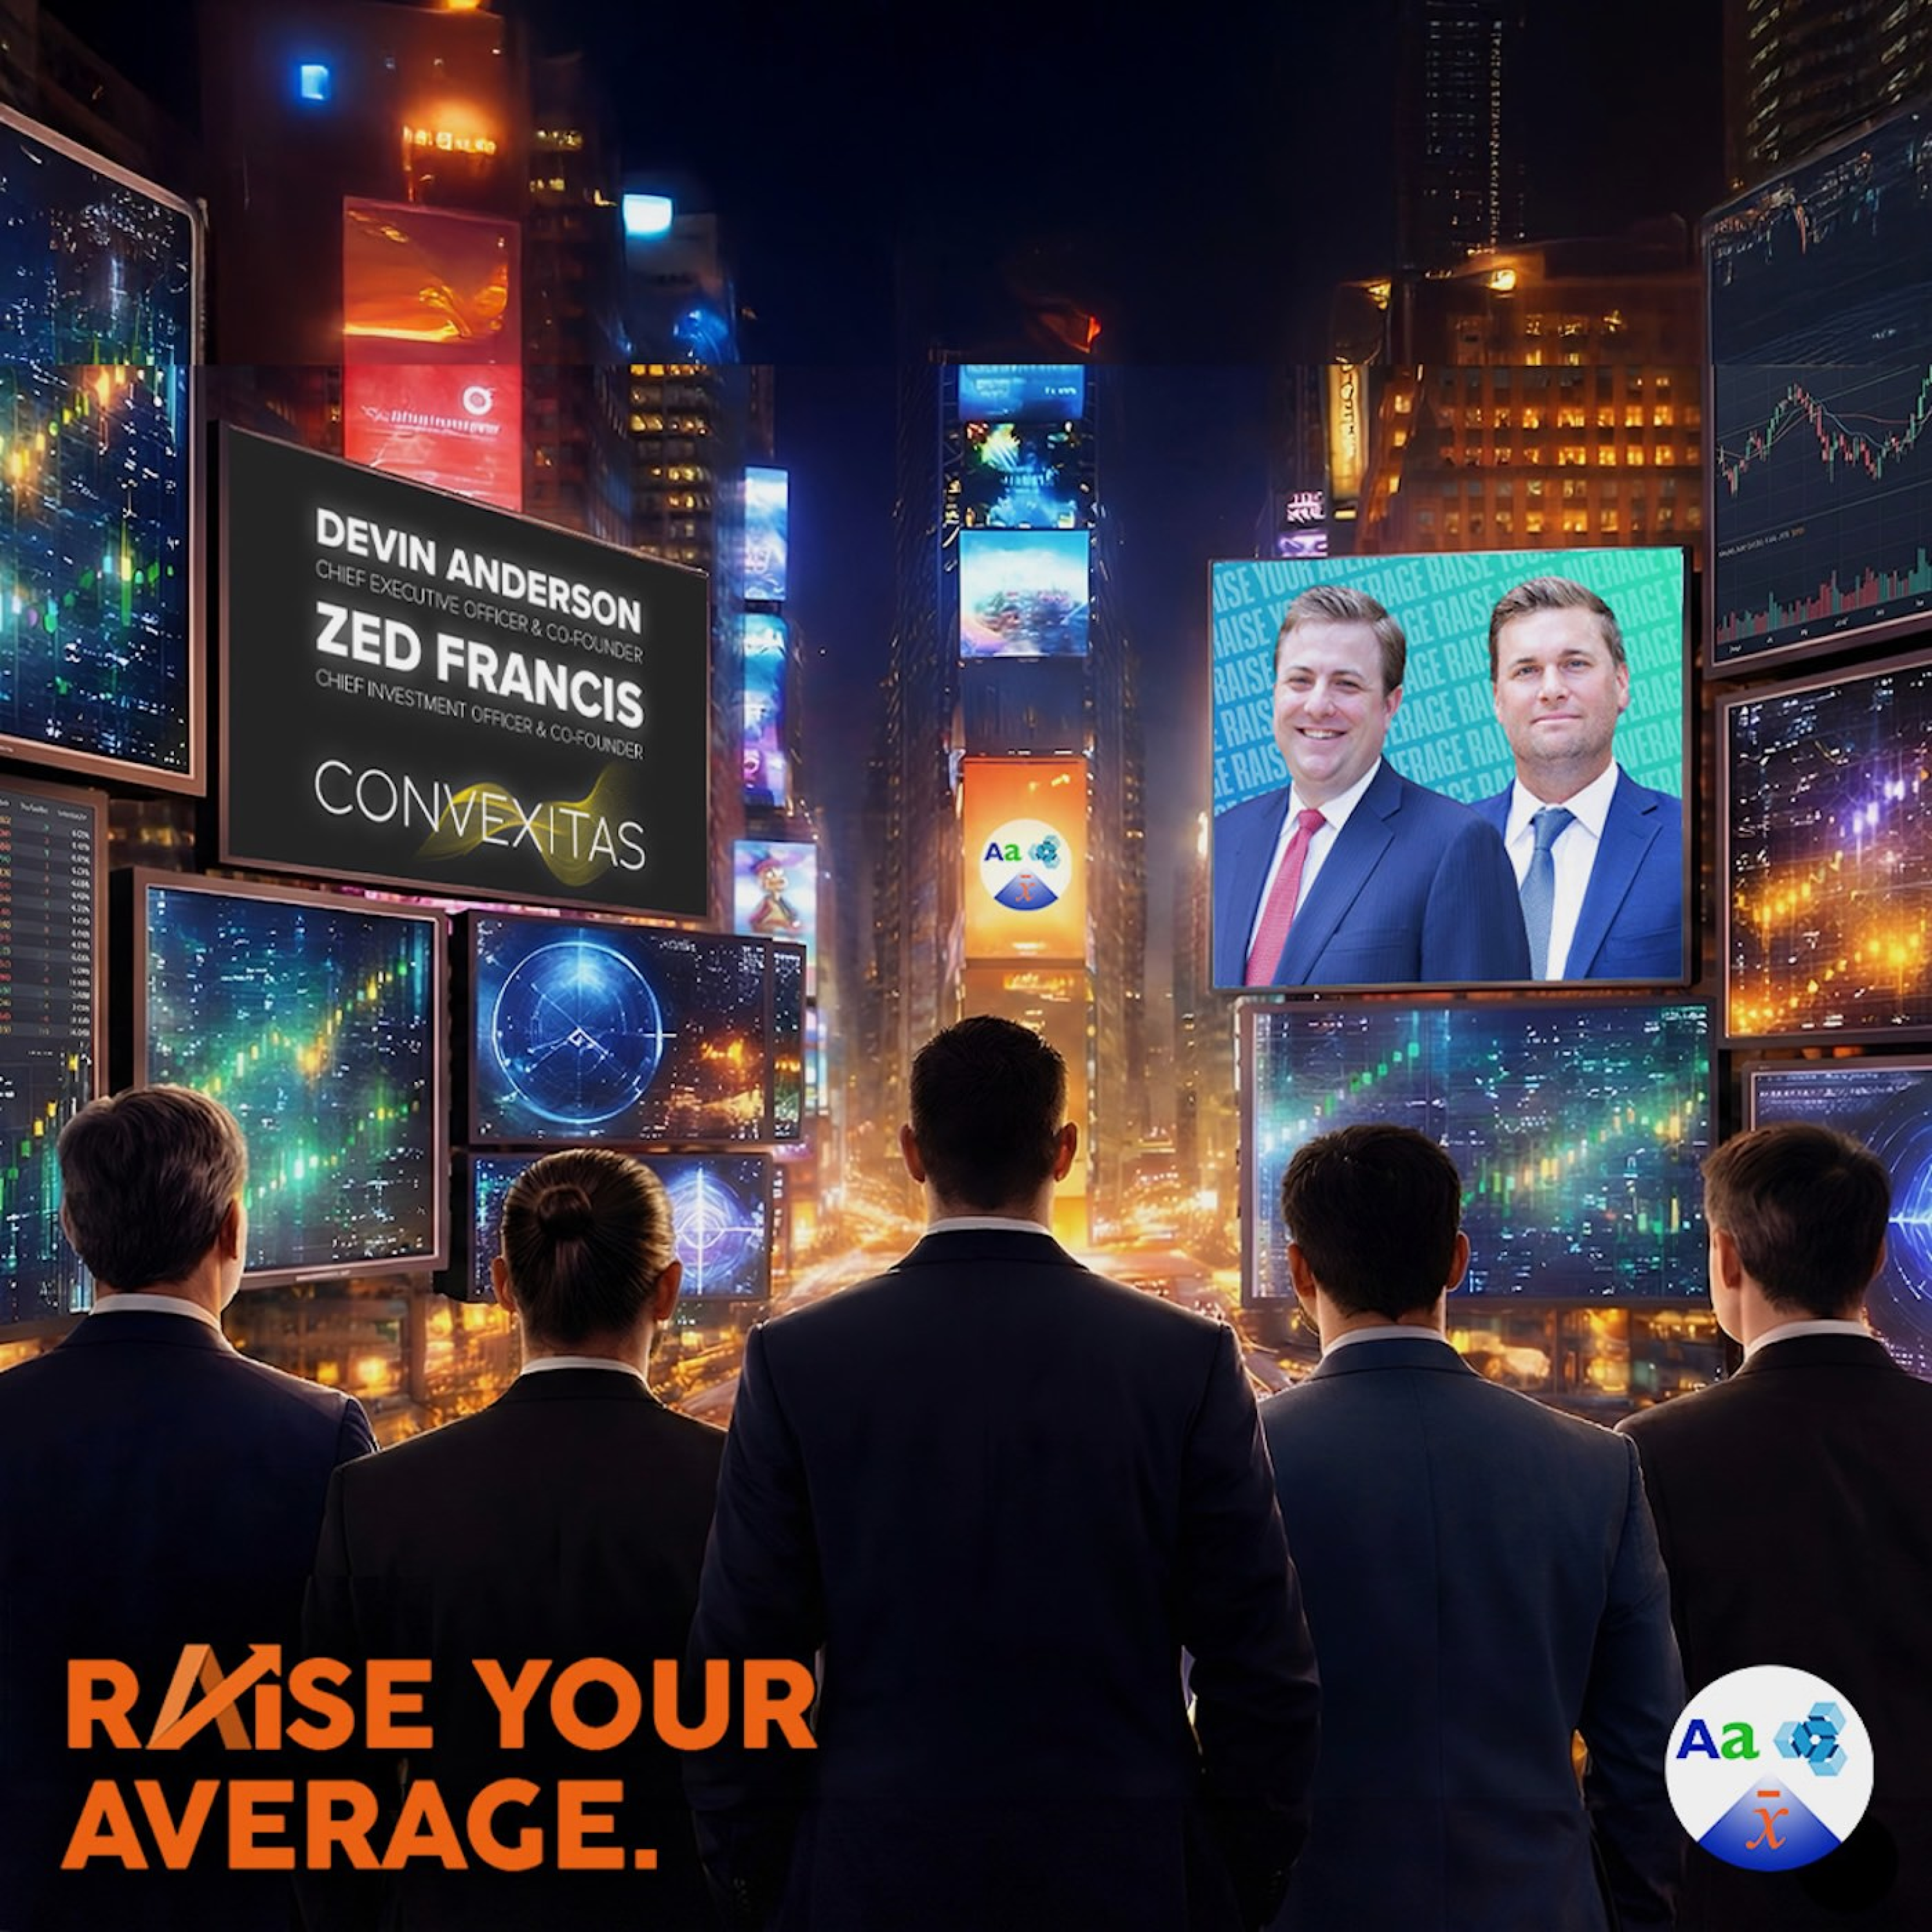
The Covered Call ETF Gap | Zed Francis and Devin Anderson
Description
Most investors think they understand what they own — Devin Anderson and Zed Francis of Convexitas are here to prove they don't, and to show what the next generation of derivative investing actually looks like.
Pierre Daillie and Mike Philbrick welcome Devin Anderson and Zed Francis, Co-Founders of Convexitas, for a masterclass in derivative investing that challenges everything advisors and investors think they know about covered calls, buffered ETFs, and options-based income strategies. Drawing on deep institutional backgrounds — Devin from two decades at Deutsche Bank's equity derivatives structuring desk, and Zed from UBS credit trading, distressed hedge funds, and Legal & General — the two founders lay bare the hidden complexity lurking inside "simple" yield products that dominate today's wealth management landscape.
The conversation pulls no punches: the hockey-stick diagrams used to explain covered call ETFs at point-of-sale actively mask real-time risk exposures that can shift dramatically intraday. A product sold as "half the risk of equities" can quietly become nearly full equity exposure within hours of a 1% market move — and most advisors and clients have no idea. Devin and Zed argue this isn't a reason to abandon these products, but a powerful case for active, continuous derivative management that delivers what the product actually promised.
The founders introduce Convexitas's philosophy: that the options market is structurally mispriced, and that most yield-seeking investors are sitting on the wrong side of that mispricing. They walk through the SMA-based approach — designed to generate accessible liquidity precisely when markets crash, enabling advisors to rebalance into distressed assets rather than being frozen by tax friction, behavioral paralysis, or trapped capital in fund wrappers. From the mechanics of short volatility to the case for unfunded overlays, return stacking, and Warren Buffett's alpha decoded through Fama-French factors, this episode is essential listening for any advisor navigating the derivative income revolution.
Chapters
00:00 — Introduction: The income wave reshaping wealth management
04:52 — Meet Devin Anderson & Zed Francis: Career arcs and the founding of Convexitas
12:16 — What investors actually own: The hidden complexity inside covered call ETFs
16:18 — Real-time risk exposure: How moneyness shifts dramatically intraday
19:17 — The silent danger: Stacking short volatility across multiple products
28:00 — Structural mispricing in the options market: Why sellers face a systemic disadvantage
38:00 — Investment products vs. trading instruments: A critical distinction for advisors
43:08 — The income stack: Gaining Gold and Bitcoin exposure with capital efficiency
50:43 — First-gen vs. next-gen: From buffered ETFs to actively managed derivative overlays
57:08 — Tax efficiency, rebalancing, and the SMA advantage
01:18:06 — Why accessible capital is the biggest benefit of risk mitigation — not mark-to-market
01:23:53 — Buying when there's blood in the streets: Liquidity, structure, and Warren Buffett's alpha
01:26:37 — Final outlook: Inflation, financialization, and the binary tail risks ahead
#CoveredCallETF #BufferedETF #DerivativeInvesting #OptionsTrading #WealthManagement #VolatilityHarvesting #ReturnStacking #TailRiskHedge #FinancialAdvisors #IncomeInvesting #PortfolioConstruction #AlternativeInvestments #RiskManagement #TaxEfficientInvesting #SMAInvesting #RaiseYourAverage #Convexitas #InvestmentStrategy #OptionsEducation #AdvisorAlpha Copyright © AdvisorAnalyst